
Prices Fell. Your Payment Didn't.
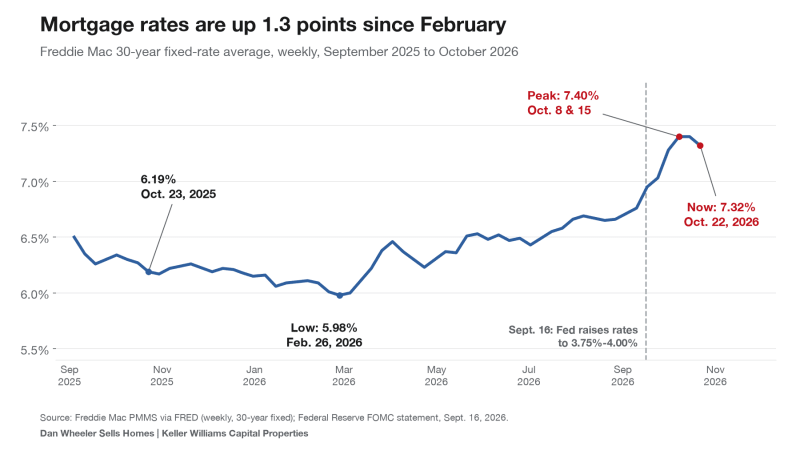
The Fed meets today and tomorrow, and the DC and Maryland housing market is already feeling the squeeze. Asking prices are down in every county I track. Mortgage rates are up 1.1 points from a year ago. Put those two things together and the monthly payment barely moved in DC and went up everywhere else. Facts over feelings, math over emotion. Let's do the math.
What Happened: The DC and Maryland Housing Market Hit a Rate Wall
On Sept. 16, the Federal Reserve raised its target range by a quarter point to 3.75% to 4.00%, according to its own statement. The next decision lands Wednesday, Oct. 28, on the Fed's meeting calendar.
Mortgage rates didn't wait. Freddie Mac's survey had the 30-year fixed at 5.98% on Feb. 26, the low for the past year. It hit 7.40% on Oct. 8 and Oct. 15, and came in at 7.32% on Oct. 22, versus 6.19% a year ago, per Freddie Mac. Next reading: Thursday, Oct. 29.
Asking Prices Are Falling Across the DC and Maryland Housing Market
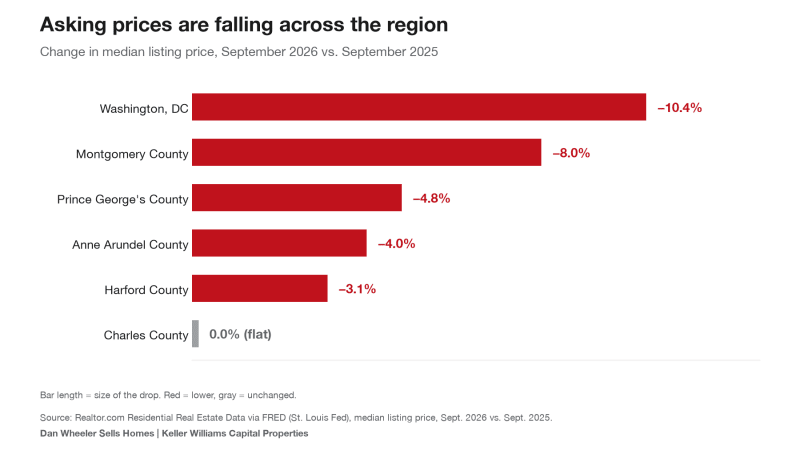
Sellers have noticed. Median listing prices in September were lower than a year earlier in DC and in five of the six places I track, and flat in Charles County, per Realtor.com data on FRED. These are asking prices, not closed sales, so treat them as a read on seller behavior.
Washington, DC Real Estate
The median listing price fell 10.4%, from $589,000 to $527,500. That is the biggest drop on the list, and it almost cancels the rate hit: the monthly payment on that median home is up just $18 (about $3,243 to $3,261).
Montgomery County Homes
Down 8.0%, from $651,826 to $599,900. The payment is still up about $120 a month, to roughly $3,709.
Prince George's County Real Estate
Down 4.8%, from $472,450 to $450,000. Payment up about $181, to roughly $2,782.
Anne Arundel County Housing Market
Down 4.0%, from $546,750 to $524,945. Payment up about $234, to roughly $3,245.
Harford County Homes
Down 3.1%, from $433,250 to $419,923. Payment up about $210, to roughly $2,596.
Charles County Real Estate
Flat at $475,000. With no price drop to cushion it, the payment jumped about $321, to roughly $2,937. That is the biggest increase of the six.
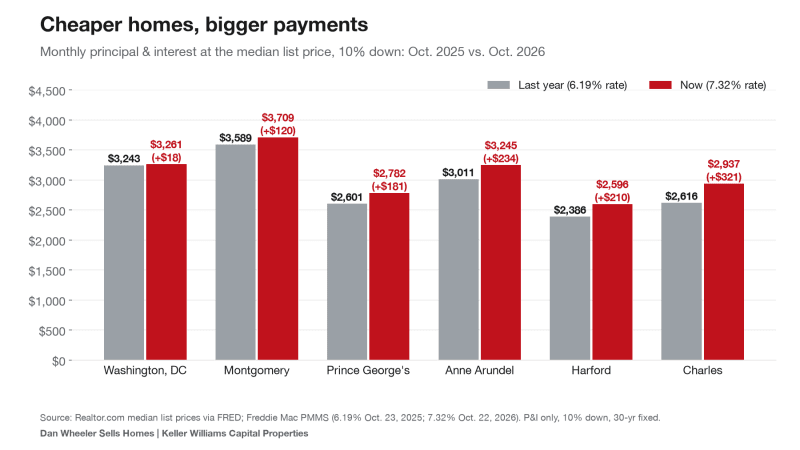
How I figured it: principal and interest only, 10% down, 30-year fixed, at 6.19% (Oct. 23, 2025) and 7.32% (Oct. 22, 2026), applied to September median list prices. Taxes, insurance and mortgage insurance are extra.
What It Means for Buyers
Here's the rule of thumb: going from 6.19% to 7.32% adds about 12% to the payment on the same loan. To hold your payment flat, the price has to fall about 11%. Only DC got close. Everywhere else, the price drop covered a fraction of the rate hike.
So the leverage isn't in the list price. It's in the negotiation. Look for homes that have already cut their price, ask for seller credits toward a rate buydown, and get real quotes from at least three lenders. A quarter point matters more than the paint color.
What It Means for Sellers
Your buyer is shopping with a payment, not a price. If your home is priced like it's still last October, the market has already told you no. Sellers who priced to the new math are the ones getting showings. Not sure where yours lands? Get a quick value check and read 4 questions to ask before selling.
Dan's Take
This part is my interpretation, not data. I don't think the Fed decision tomorrow changes much for your mortgage on its own, because mortgage rates track longer-term bond yields, not the Fed's overnight rate. But the tone of the press conference can move rates for a few days. If you're under contract or about to lock, ask your lender what happens to your rate if it moves, and don't try to time a one-day swing. Most people trying to be clever with rate locks end up paying for it.
Final Takeaway
Don't ask "is it a good time to buy?" Ask "what payment can I live with, and which homes get me there?" Then run that number at today's rate. Action item: before you tour another house, get a payment estimate at 7.3% on your target price, and a second one at 6.8% in case rates ease. If both work, you're ready. If only the second one works, you have a plan to make, and I'm happy to walk you through it.
FAQ: DC and Maryland Housing Market and Rates
Will the Fed's decision lower my mortgage rate?
Not directly. Mortgage rates follow longer-term bond yields. The Fed's moves and its messaging can nudge those yields, but they don't set your rate.
Are home prices actually dropping in DC and Maryland?
Asking prices are lower than a year ago in DC and five of the six places I track, based on Realtor.com data. Closed sale prices may differ. Ask me for a recent sales comparison for your street.
Should I wait for rates to come down?
Nobody knows where rates are going, me included. A better test: can you afford the payment today, and would you be fine if you could refinance later? If yes, a good house doesn't need to wait for a perfect rate.
Dan Wheeler | Keller Williams Capital Properties
Contact Dan · What's My Home Worth? · Schedule a Call · (301) 806-3179
Sources: Federal Reserve (FOMC statement, Sept. 16, 2026; 2026 meeting calendar); Freddie Mac Primary Mortgage Market Survey via FRED; Realtor.com Residential Real Estate Data via FRED. Payment figures are my own calculations and are estimates for education only, not a loan offer or financial advice. Data as of Oct. 27, 2026.