
The Fed Wants to Hike Again. Buyers Are Already Gone.
Mortgage rates have been drifting down for a month, and I know some of you were starting to hope. Then the Federal Reserve released its meeting minutes on Wednesday, and the hope took a hit. For anyone watching the DC and Maryland housing market, the short version is this: the Fed is not close to cutting, and local buyer activity is already running slower than it was a year ago.
What Happened: The Fed Minutes and a Quiet Buyer Pool
The minutes cover the Oct. 27-28 meeting, where the Fed held its rate at 3.75%-4.00%. The vote was 10-2, and the two dissenters, Lisa Cook and Beth Hammack, wanted to raise rates by a quarter point right then. According to the minutes, some of the officials who voted to hold described it as a close call, and nearly all participants agreed rates would need to go higher to get inflation back to 2%. A couple even said a hike bigger than 25 basis points could be on the table if inflation data come in hot (ABA Banking Journal). The next meeting is Dec. 8-9, and futures markets are pricing a hike as very likely, above 90% in the sources I checked.
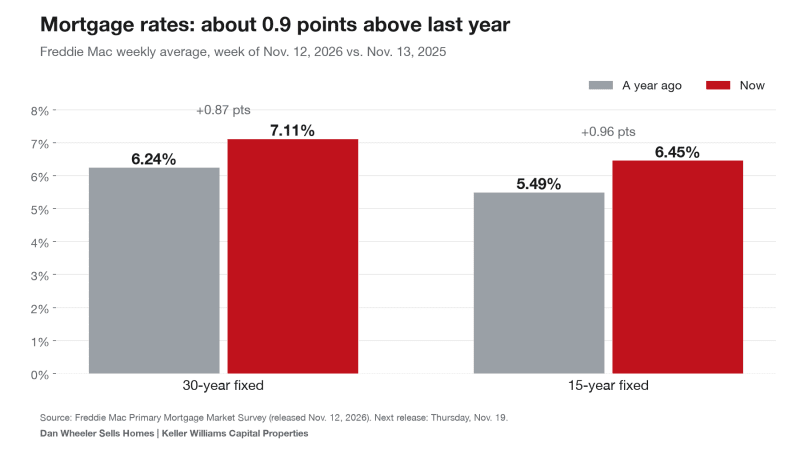
The Fed does not set mortgage rates directly, so this does not mean your rate jumps by the same amount. But it does mean the relief we have seen is fragile. Freddie Mac's 30-year average fell four weeks in a row to 7.11% on Nov. 12, the lowest in seven weeks (Freddie Mac). That is still 0.87 points above the 6.24% a year ago. The next reading comes out today, Thursday, Nov. 19.
The DC and Maryland Housing Market: Buyers Are Pulling Back
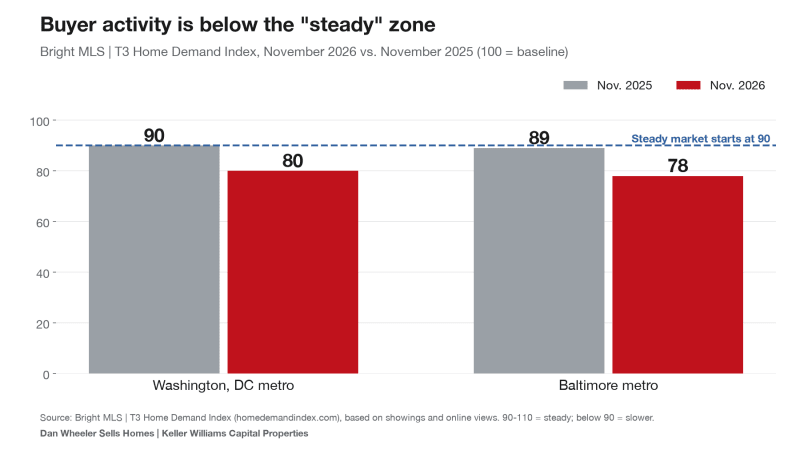
Here is the part I find more useful than any Fed headline. The Bright MLS | T3 Home Demand Index, which tracks showings and online views before a sale happens, put the Washington metro at 80 in November. That is labeled "Slow" and down from 90 a year ago. The Baltimore metro is at 78, down from 89 (Home Demand Index). On this index, 90 to 110 is a steady market, so both of our regions are below it.
This lines up with what Bright MLS economist Lisa Sturtevant said earlier this month: she expects the Washington-area market to stay sluggish through the end of the year, with sellers likely to cut prices and offer concessions in the last two months (FFXnow).
What 7.11% Costs, County by County
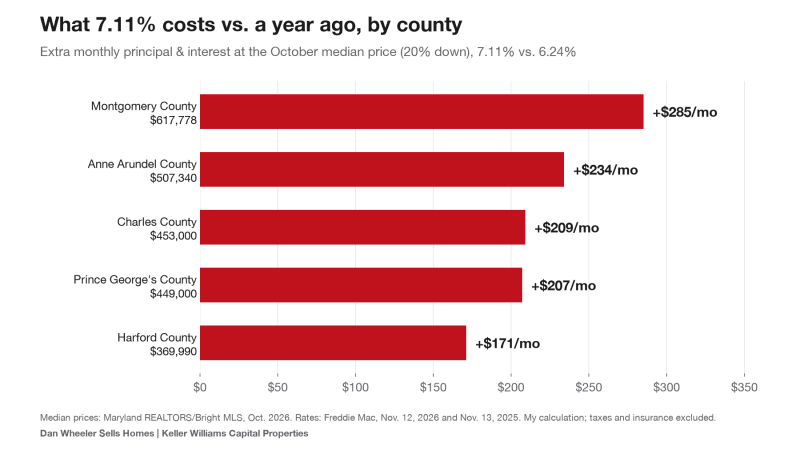
I took each county's October median sold price from Maryland REALTORS (Bright MLS data), assumed 20% down, and compared the monthly principal and interest at 7.11% with 6.24%, last year's rate. Taxes and insurance are not included.
Washington, DC Real Estate
I could not verify DC-only buyer-activity numbers today, so I will stick to the metro reading above. The DC metro index covers the District plus Montgomery and Prince George's counties, among others.
Montgomery County Homes
On a $617,778 median, the payment is about $3,325 a month, roughly $285 more than a year ago. Montgomery has the biggest dollar hit because it has the highest price.
Prince George's County Real Estate
On a $449,000 median, the payment is about $2,416, up about $207 a month.
Anne Arundel County Housing Market
On a $507,340 median, the payment is about $2,730, up about $234. Anne Arundel is counted in the Baltimore-area demand reading.
Harford County Homes
On a $369,990 median, the payment is about $1,991, up about $171, the smallest increase of the five. Harford also falls in the Baltimore-area reading.
Charles County Real Estate
On a $453,000 median, the payment is about $2,438, up about $209. Charles is not broken out in either demand index, so I will not guess at its buyer activity.
A Quick Look at Northern Virginia
Fairfax County closed 810 homes in October, down 21.7%, so the same slowdown is showing up across the river (FFXnow).
What It Means for Buyers
Do not time the Fed. Nobody, including the Fed, knows where rates land in March. What you can control is your leverage: with demand this soft, sellers are more willing to talk about repairs, closing-cost credits and rate buydowns. Get a written quote from a lender now so you know your real payment, and read my buyer guide before you tour.
What It Means for Sellers
If fewer buyers are showing up, the ones who do are serious and comparing you with every other listing. Price to the last 90 days of closed sales, not to last spring. Find out what your home is worth and see 4 questions to ask before selling.
Dan's Take
This is my interpretation, not data. A year ago, buyers could at least hope the Fed was heading toward cuts. Now the minutes say the next move is more likely up, and I think that is why showings are fading even as the 30-year rate eased. People do not wait on a number; they wait on a direction. Math over emotion: on a $400,000 loan, a quarter-point change in rate is only about $68 a month, so negotiate the whole deal (price, credits, repairs), not just the rate.
Final Takeaway
The Fed is signaling higher, buyer activity is below normal, and prices are holding because most owners can wait. That is a negotiating market, not a panic market. Action item: ask a lender for your exact payment at today's rate and at a rate 0.5 points higher, so you know your limit before you fall in love with a house.
FAQ: The DC and Maryland Housing Market
Will mortgage rates go up if the Fed hikes in December?
Not necessarily by the same amount. Mortgage rates follow the bond market's expectations, and a hike that is already priced in often moves them very little.
What is the Home Demand Index?
It is a Bright MLS | T3 measure of pre-sale activity such as showings and online views. Below 90 signals a slower market.
Is it a good time to buy in Maryland?
Buyers have more leverage than a year ago, but rates are high. Run your own payment numbers before deciding.
Dan Wheeler | Keller Williams Capital Properties
Contact Dan · What's My Home Worth? · Schedule a Call · (301) 806-3179
Sources: FOMC minutes of the Oct. 27-28, 2026 meeting (released Nov. 18) via ABA Banking Journal; Freddie Mac PMMS (Nov. 12, 2026); Bright MLS | T3 Home Demand Index, Nov. 2026; Maryland REALTORS Housing Statistics, Oct. 2026; FFXnow, Nov. 12, 2026. Monthly payments are my calculation (30-year fixed, 20% down, principal and interest only). For education only, not financial advice. Data as of Nov. 19, 2026.