
The Fed Held. Two Voters Wanted a Hike.
The Fed left rates alone on Wednesday, but if you're shopping in the DC and Maryland housing market, don't breathe out yet. Two of the twelve voters wanted to raise rates, and mortgage rates are already near their highest level in a year. Facts over feelings, math over emotion: here's what a rate hike scenario would cost a buyer in DC, Montgomery, Prince George's, Anne Arundel, Harford and Charles counties.
What Happened: The Fed Held Rates, With Two Votes to Raise
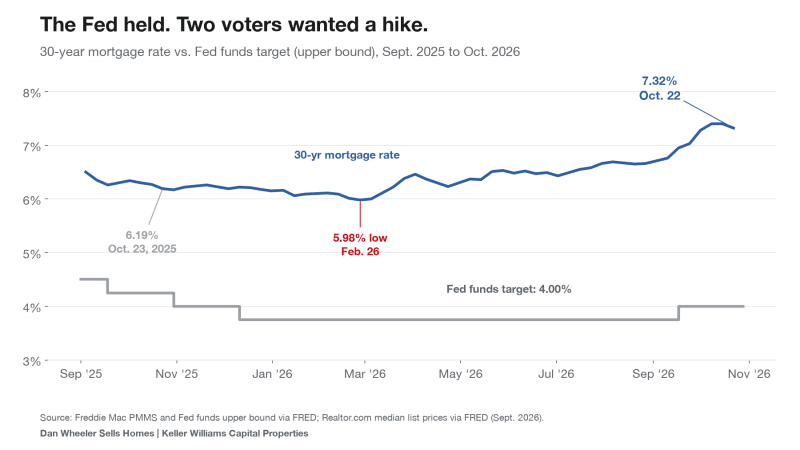
On Oct. 28, the Federal Reserve kept its target range at 3-3/4 to 4 percent. The vote was 10–2. Lisa Cook and Beth Hammack voted against the decision because they preferred to raise the range by a quarter point, according to the Fed's statement. The statement also says "Inflation remains elevated." The Fed already raised rates once this year, on Sept. 16.
Mortgage rates don't follow the Fed's overnight rate one for one, but they have moved the wrong way anyway. Freddie Mac's 30-year average hit a 2026 low of 5.98% in February. It was 7.32% on Oct. 22, down from 7.40% the week before, and 6.19% a year ago, per Freddie Mac. The next reading comes out today, Thursday, Oct. 29.
What a Rate Hike Scenario Costs in the DC and Maryland Housing Market
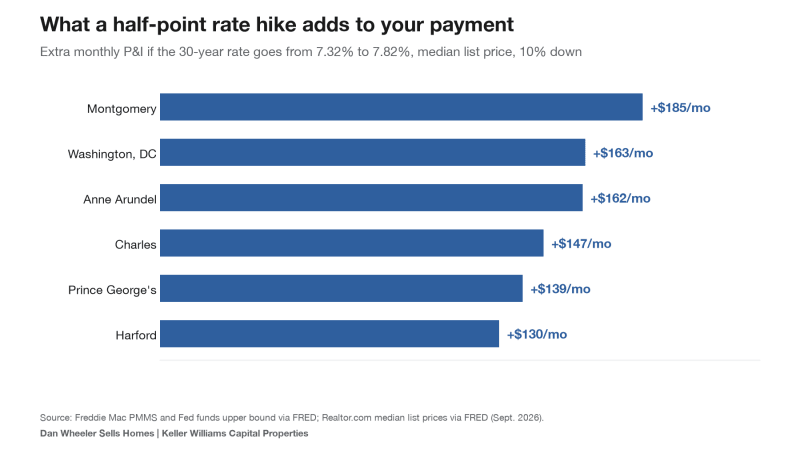
I can't tell you where rates go next, and neither can anyone else. What I can do is show you what each move costs. Take Montgomery County's median list price of $599,900 with 10% down. At 7.32%, principal and interest is about $3,709 a month. A half-point increase to 7.82% adds $185. A half-point drop to 6.82% would take off roughly the same.
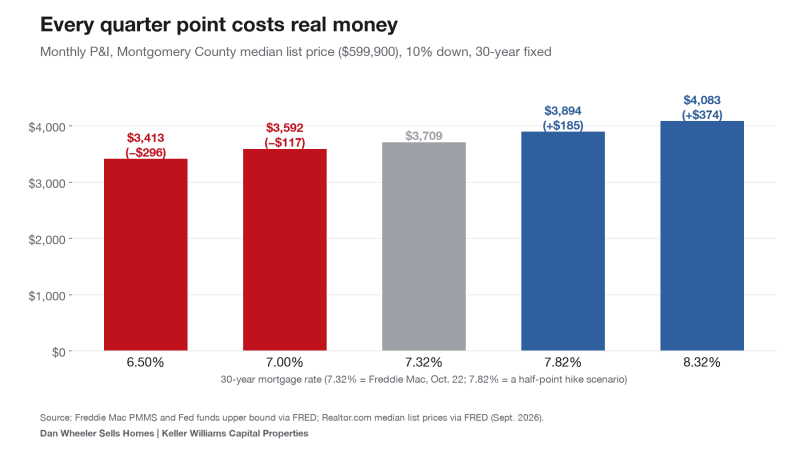
The same half-point hits every county, scaled to its price. I used the Sept. 2026 median list price from Realtor.com data on FRED for each place.
Washington, DC Real Estate
Median list price $527,500. A half-point increase adds about $163 a month on a 10%-down loan, taking P&I from $3,261 to $3,424.
Montgomery County Homes
The highest price in my set, $599,900, so the biggest hit: +$185 a month ($3,709 to $3,894).
Prince George's County Real Estate
Median list price $450,000. Add about $139 a month ($2,782 to $2,921).
Anne Arundel County Housing Market
Median list price $524,945. Add about $162 a month ($3,245 to $3,408).
Harford County Homes
Median list price $419,923, the lowest of the six. A half-point costs about $130 a month ($2,596 to $2,726).
Charles County Real Estate
Median list price $475,000. Add about $147 a month ($2,937 to $3,083).
All figures are principal and interest only, 30-year fixed, 10% down. Taxes, insurance and mortgage insurance are extra. Rates are Freddie Mac's national average, not a quote.
What It Means for Buyers
Nobody can time the rate. Don't try to. If you're ready and the numbers work today, the question is whether you can afford the payment at 7.82% without panic, because that's the stress test. If you can, you're covered either way. If you can't, you want a different price range, not a hope that rates fall. Ask your lender about a rate lock and about whether a buydown from the seller makes sense. Start with my buyer checklist and get your numbers before you tour.
What It Means for Sellers
Every extra $150 on a monthly payment shrinks the pool of buyers who qualify at your price. If rates keep rising, your buyers' budgets shrink with them. Price for the payment buyers can actually afford, not the number you saw last spring. Curious where you stand? Get a quick value check and read 4 questions to ask before selling.
Dan's Take
This part is my interpretation, not data. A split vote with two hawks tells me the Fed's next move is not guaranteed to be a cut, and the market knows it. I'd stop planning around the rate drop everyone keeps promising and plan around the payment you can carry today. The rate is a number you can refinance later. The price you pay isn't.
Final Takeaway
The Fed held, but the risk tilted toward higher rates, and a half-point costs $130 to $185 a month depending on where you buy. Action item: ask your lender to run your payment at today's rate and at one half-point higher, and only shop in the range where both work. Happy to connect you with lenders I trust.
FAQ: Fed Decisions and Mortgage Rates in the DC and Maryland Housing Market
Did the Fed raise rates on Oct. 28?
No. It held the target range at 3-3/4 to 4 percent. Two members voted for a quarter-point increase.
Does the Fed set my mortgage rate?
Not directly. Mortgage rates track longer-term bond yields and investor expectations, so they can move with Fed signals even when the Fed doesn't change its own rate.
Should I wait for rates to come down before buying?
It depends on your payment, your timeline and your local market. Run the numbers at today's rate and at a higher one. If the payment works, waiting is a bet, not a plan.
Dan Wheeler | Keller Williams Capital Properties
Contact Dan · What's My Home Worth? · Schedule a Call · (301) 806-3179
Sources: Federal Reserve FOMC statement, Oct. 28, 2026; Freddie Mac Primary Mortgage Market Survey (30-year fixed, via FRED); Realtor.com median listing prices via FRED (Sept. 2026). Payment figures are my own calculations. For education only, not financial advice. Data as of Oct. 29, 2026.